UAE property terms, in plain words.
70 terms a buyer meets. Each has a sentence or two, its formula where there is one, and what the figure leaves out.
Longer explanations are in the guides. Figures the calculator holds are read from it, so a definition cannot disagree with a calculation.
A
- Amortisation
Paying a loan off by regular instalments. Each one is part interest and part repayment, and the interest share is largest at the start.
See also mortgage, principal. Guide: Mortgages: the deposit, the rate and the term.
- Appreciation
Another word for capital growth.
See capital growth.
- Asking price
What a seller advertises a property for. It is where a negotiation starts.
What it leaves out. What homes like it sold for. That is the registered price.
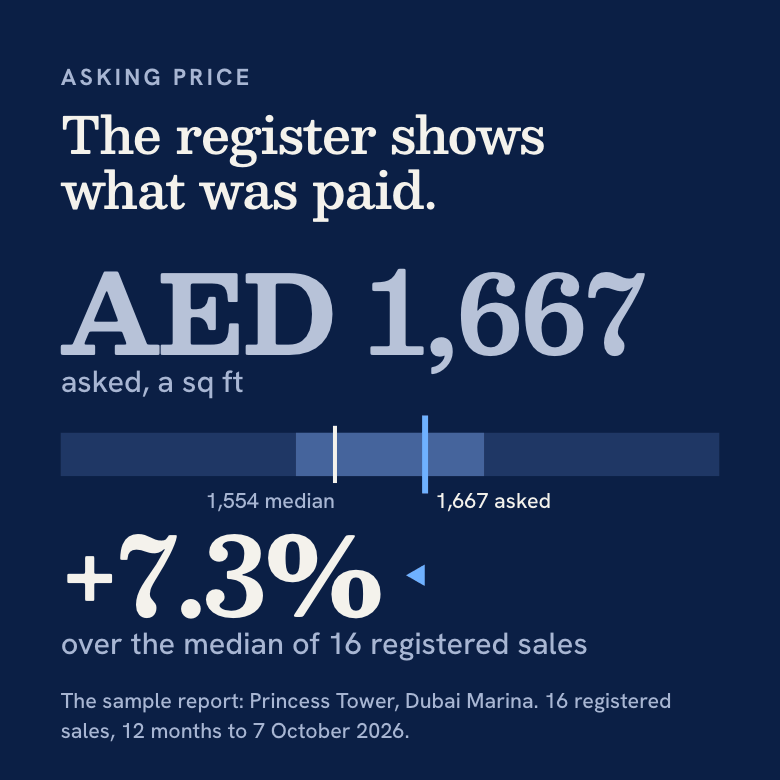
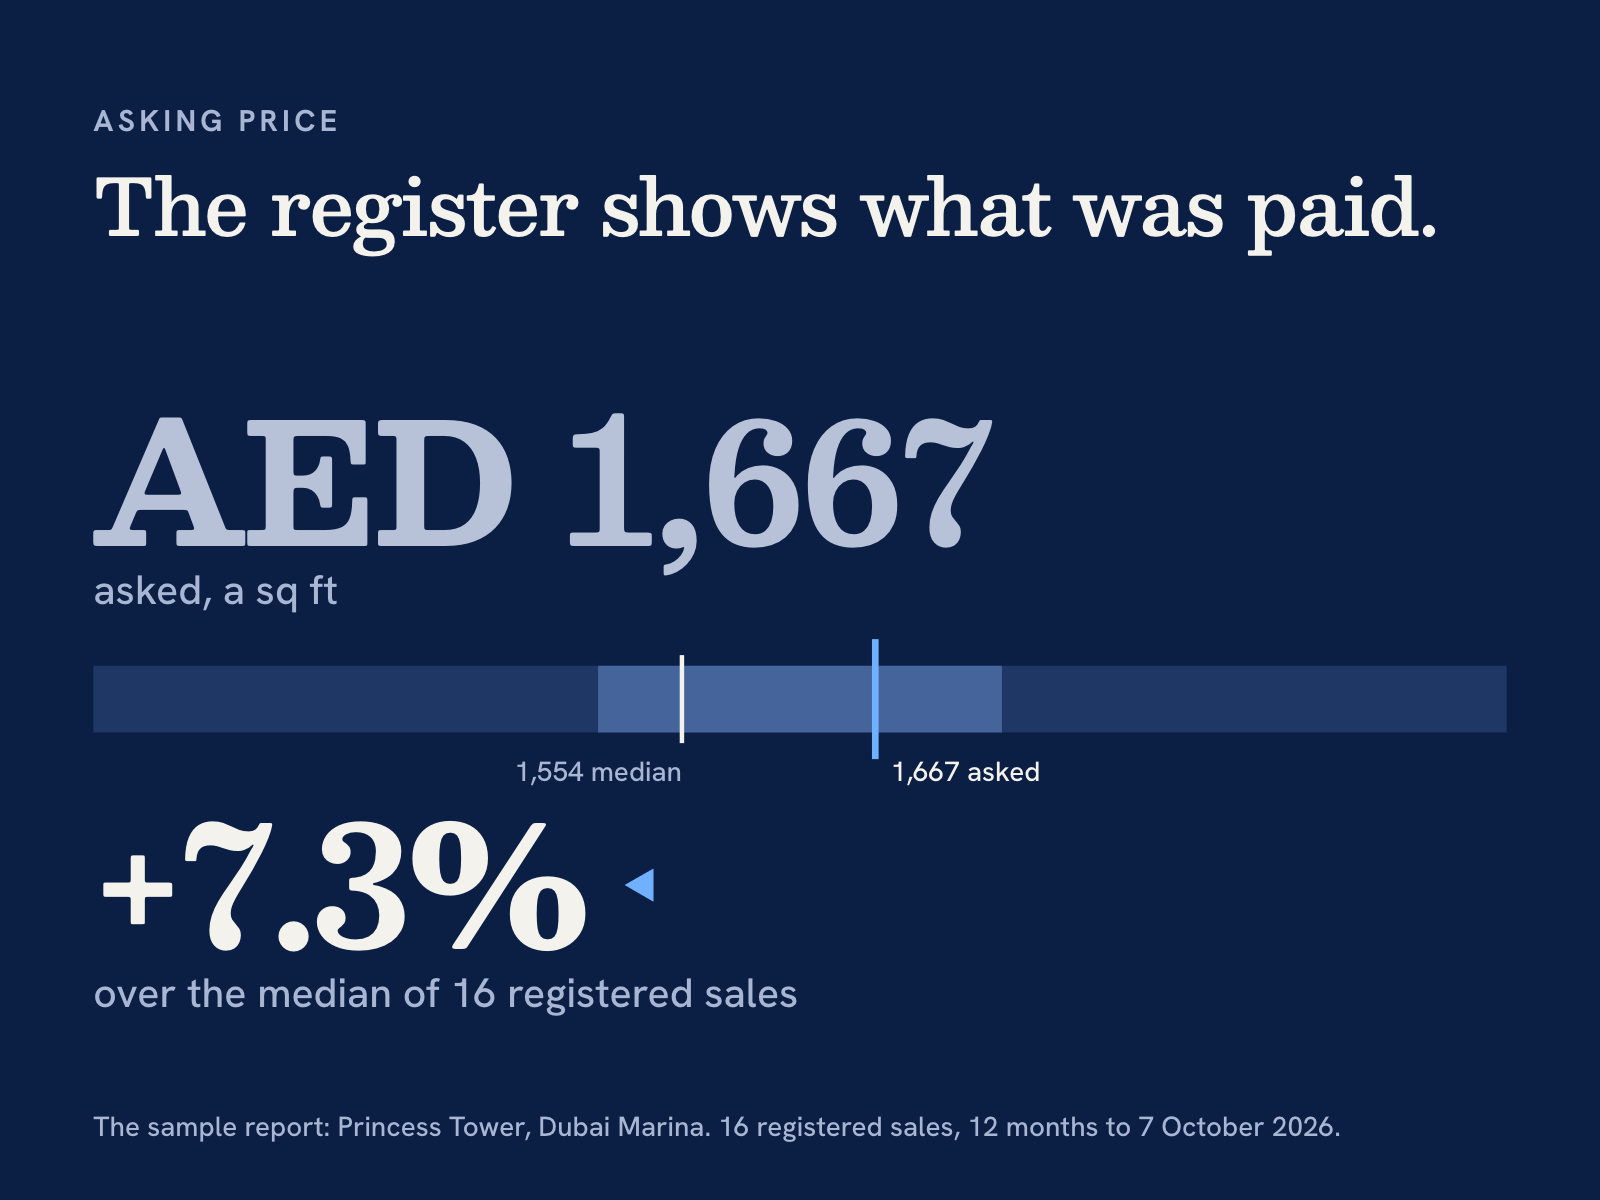
Asked, and registeredA portal shows what sellers hope for; the register shows what was paid. The 16 sales registered in Princess Tower in the 12 months to 7 October 2026 have a median of AED 1,554 a sq ft, and the middle half lie between AED 1,505 and AED 1,741. Dubai Land Department, Real Estate Transactions, open data via Data Dubai. Worked on the sample report’s property: a one-bedroom flat of 870 sq ft in Princess Tower, Dubai Marina, at AED 1,450,000. The asking price and the rent expected are an example of ours, entered for the sample report. They are not a listing. Registered figures read . Contains information originated by the Dubai Land Department and the Dubai Data and Statistics Establishment, obtained from Data Dubai (https://data.dubai) under its Open Data Licence. Every figure is YieldPulse’s own calculation from that information. YieldPulse is an independent product. It is not produced by, affiliated with, authorised by or endorsed by the Dubai Land Department, the Dubai Data and Statistics Establishment, Data Dubai or the Government of Dubai. See also registered price.
- Asking rent
The rent a landlord advertises, before any negotiation.
What it leaves out. What tenants agreed to pay. That is in the registered rent contracts.
See also registered rent, gross yield.
B
- Base rate
The Central Bank of the UAE’s own policy rate. It has been 3.90% since 17 September 2026.
What it leaves out. What a borrower pays. A bank prices a mortgage above it.
See also EIBOR, interest rate.
- Break-even occupancy
The share of the year a property must be let for the rent to cover every cost of holding and the mortgage.
(Costs of holding + mortgage payments) ÷ a full year’s rent × 100
What it leaves out. Capital growth, and the part of each mortgage payment that repays the loan.
See also vacancy, cash flow. Guide: Gross yield, net yield and cash flow.
- Buying costsAlso closing costs
Everything paid on top of the price: the transfer fee, the trustee, the agent, the bank’s fees and the registrations. On a Dubai purchase at AED 1,000,000 with a loan of AED 800,000 the calculator counts AED 86,260.
See also DLD transfer fee, cash needed. Guide: What it costs to buy.
C
- Capital growthAlso appreciation
A rise in what a property is worth. The yearly rate you give the calculator is an assumption, and we do not forecast one.
What it leaves out. Any promise that it will happen. Set it to zero to see the purchase stand on its rent alone.
See also total return, stress test.
- Capitalisation rateAlso cap rate
Net operating income as a share of the price. It is the same sum as net yield under another name.
Net operating income ÷ price × 100
See also net yield, net operating income.
- Cash flow
What is left of the rent after every cost of holding and the mortgage payment, by the month or the year. A negative figure is money you add from your own income.
Net operating income − mortgage payments
What it leaves out. The part of each mortgage payment that repays the loan, which comes back when you sell.
See also net operating income, cash-on-cash return. Guide: Gross yield, net yield and cash flow.
- Cash neededAlso initial investment
The deposit plus every buying cost: what must be in your account on the day of the transfer.
Deposit + buying costs
What it leaves out. Furniture, repairs and a reserve for empty months.
See also deposit, buying costs. Guide: What it costs to buy.
- Cash-on-cash return
A year’s cash flow as a share of the cash you put in. It measures the return on your own money after the bank has been paid.
Yearly cash flow ÷ cash needed × 100
What it leaves out. Capital growth, and the part of the loan you have repaid.
See also cash flow, cash needed, leverage. Guide: Gross yield, net yield and cash flow.
- Chiller charges
What a district cooling company bills for air conditioning. Some buildings include it in the service charge, and in others the owner or the tenant is billed separately.
See also service charge.
- Closing costs
Another name for buying costs.
See buying costs.
- Corporate tax
A federal tax of 9% on a business’s taxable income above AED 375,000. Ordinary rent earned by an individual is outside it; a company’s rent is not.
See also holiday-home permit. Guide: Tax on rent in the UAE.
D
- Data Dubai
The emirate’s open-data portal. The Dubai Land Department publishes registered sales, rent contracts and building service charges through it.
See also Dubai Land Department, registered price.
- DepositAlso down payment
The part of the price you pay yourself. The Central Bank of the UAE sets the least a bank may accept from an expatriate: 20% under AED 5,000,000 and 30% at or above for a first mortgaged property, 40% for a second or later one, and 50% off-plan.
See also loan to value, cash needed. Guide: Mortgages: the deposit, the rate and the term.
- Depreciation
A fall in what a property is worth. The stress test shows what one would do to a purchase.
See also stress test, capital growth.
- DEWA
Dubai Electricity and Water Authority, which supplies water and power in Dubai. The calculator allows AED 2,500 to connect a property.
- DLD transfer feeAlso transfer fee
The Dubai Land Department’s fee for registering a sale: 4% of the price. The department lists it as half from each side, and contracts usually put all of it on the buyer.
Price × 4%
See also buying costs, title deed. Guide: What it costs to buy.
- Dubai Land DepartmentAlso DLD
The government department that registers sales, mortgages and tenancies in Dubai. We name it as the source of registered figures; it does not endorse this site.
See also Data Dubai, RERA.
E
- Early settlement
Paying a mortgage off before its term ends, as a sale does. The Central Bank of the UAE caps the bank’s fee at 1% of the balance or AED 10,000, whichever is less.
See also mortgage, refinancing.
- EIBOR
The Emirates Interbank Offered Rate: what UAE banks charge each other to borrow dirhams. On 9 October 2026 it stood at 4.19% for three months, 4.55% for six months and 4.84% for one year (Central Bank of the UAE).
What it leaves out. The bank’s margin, which is added on top to price a variable mortgage.
See also variable rate, base rate. Guide: Mortgages: the deposit, the rate and the term.
- Ejari
Dubai’s register of tenancy contracts. A tenancy has to be registered, and the calculator allows AED 220 for it.
See also tenancy contract, registered rent.
- Equity
The share of a property that is yours: what it is worth, less what you owe on it. It grows as the loan is repaid and moves with the value.
Value − loan outstanding
See also loan to value, principal.
- Escrow account
A bank account that holds buyers’ payments for an off-plan project apart from the developer’s own money.
See also off-plan, payment plan. Guide: Off-plan and payment plans.
F
- Fixed rate
A mortgage rate held for an agreed number of years. When the fixed period ends, the loan moves to a variable rate.
See also variable rate, interest rate.
- Freehold
Ownership of a property and its land with no end date. A buyer from outside the UAE and the Gulf states can hold freehold only in the areas an emirate has designated for it.
See also leasehold, title deed.
G
- Gross yield
A year’s rent as a share of the price, before any cost. It is the figure an advertisement quotes.
Yearly rent ÷ price × 100
What it leaves out. The service charge, maintenance, management, insurance, empty months and every buying cost.
See also net yield, asking rent. Guide: Gross yield, net yield and cash flow.
H
- Handover
The day a developer gives the buyer the keys to a finished off-plan property. Rent can only start after it.
See also off-plan, payment plan.
- Holding costsAlso operating expenses, running costs
What a property costs to own each year whether or not it is let: the service charge, maintenance, management and insurance.
What it leaves out. The mortgage. That is financing, and cash flow counts it.
See also service charge, net operating income.
- Holiday-home permit
A permit from an emirate’s tourism department to let a home by the night. For tax it counts as a licence, so the income is tested as a business: an individual is taxed only if business turnover passes AED 1,000,000 in a calendar year.
See also corporate tax. Guide: Tax on rent in the UAE.
- Home insurance
Cover for the property and, if you choose, what is in it. The calculator starts from AED 2,000 a year for an apartment in Dubai.
See also holding costs.
I
- Initial investment
Another name for cash needed.
See cash needed.
- Interest rate
What a bank charges for a loan, as a yearly percentage of what you owe. Use the rate your bank quotes you: the calculator only starts from a reference rate, and shows the day it was last reviewed.
See also EIBOR, base rate, fixed rate, variable rate. Guide: Mortgages: the deposit, the rate and the term.
- Internal rate of returnAlso IRR
The yearly rate of return on a purchase once the timing of every payment is counted: the cash in at the start, each year’s cash flow and the sale.
What it leaves out. The growth rate and the sale price, which are assumptions. Change them and it changes.
See also return on investment, total return.
J
- Jointly owned propertyAlso strata
A building or community divided into units that are owned separately and common parts that the owners share. The owners pay for the common parts through the service charge.
See also service charge.
L
- Leasehold
The right to hold a property for a fixed number of years. When the term ends, the property goes back to the freeholder.
See also freehold.
- Leverage
Buying with borrowed money. A rise or a fall in the property’s value then lands on your deposit alone, so gains and losses are both larger as a share of the cash you put in.
See also loan to value, cash-on-cash return. Guide: Mortgages: the deposit, the rate and the term.
- Liquidity
How quickly something can be turned into cash. A property takes time to sell and costs money to sell.
- Loan to valueAlso LTV
The loan as a share of the property’s value. The Central Bank of the UAE caps it for an expatriate at 80% under AED 5,000,000 and 70% at or above for a first mortgaged property, 60% for a second or later one, and 50% off-plan.
Loan ÷ value × 100
See also deposit, leverage. Guide: Mortgages: the deposit, the rate and the term.
M
- MaintenanceAlso maintenance reserve
Money set aside each year for repairs inside the property: air conditioning, plumbing, repainting between tenants. The calculator starts from AED 4 a sq ft a year for an apartment in Dubai.
What it leaves out. The common parts of the building. The service charge pays for those.
See also holding costs, service charge.
- Market value
What a property would sell for on a given day between a willing buyer and a willing seller. A bank’s valuer estimates it; a YieldPulse report does not, and shows what was registered and what is asked.
See also registered price, asking price.
- Median
The middle value when figures are put in order: half are below it and half above. A report uses it for registered prices and rents, because a few unusual sales cannot pull it far.
See also registered price, registered rent.
- Mortgage
A loan secured on the property and repaid monthly. The Central Bank of the UAE allows a term of up to 25 years.
See also loan to value, interest rate, amortisation. Guide: Mortgages: the deposit, the rate and the term.
- Mortgage registration fee
The Dubai Land Department’s fee for registering the bank’s charge over the property: 0.25% of the loan plus AED 270. On a loan of AED 800,000 that is AED 2,270.
Loan × 0.25% + AED 270
See also buying costs, mortgage.
N
- Net operating incomeAlso NOI
A year’s rent, less empty months and every cost of holding, before the mortgage. It is what the property earns, however it was paid for.
Rent collected − holding costs
What it leaves out. The mortgage, the buying costs and any tax.
See also net yield, holding costs, cash flow.
- Net yield
Net operating income as a share of the price: what a property returns after the costs of holding it. It is the same for a cash buyer and a borrower.
Net operating income ÷ price × 100
What it leaves out. The mortgage, the buying costs and any change in what the property is worth.
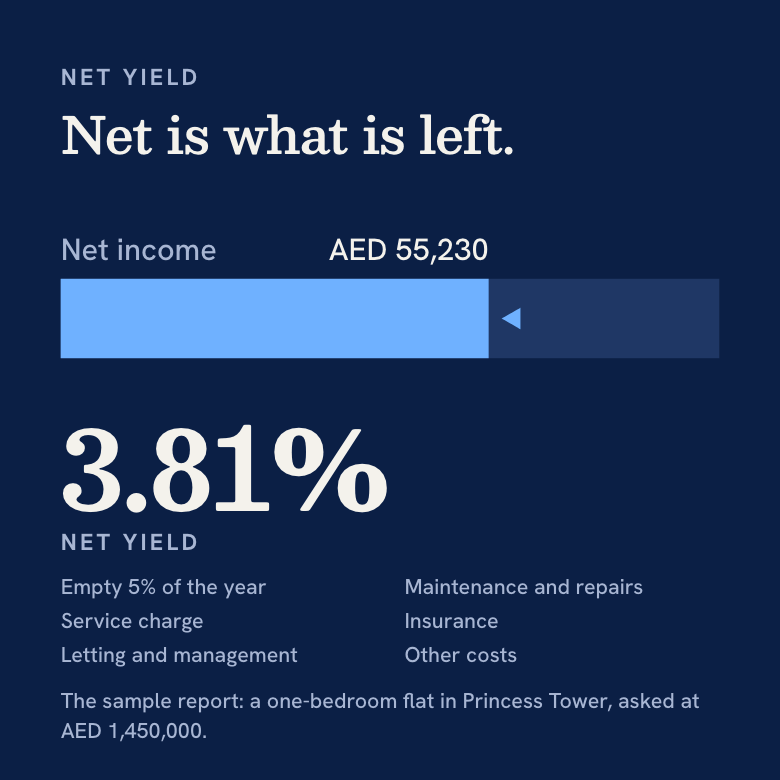
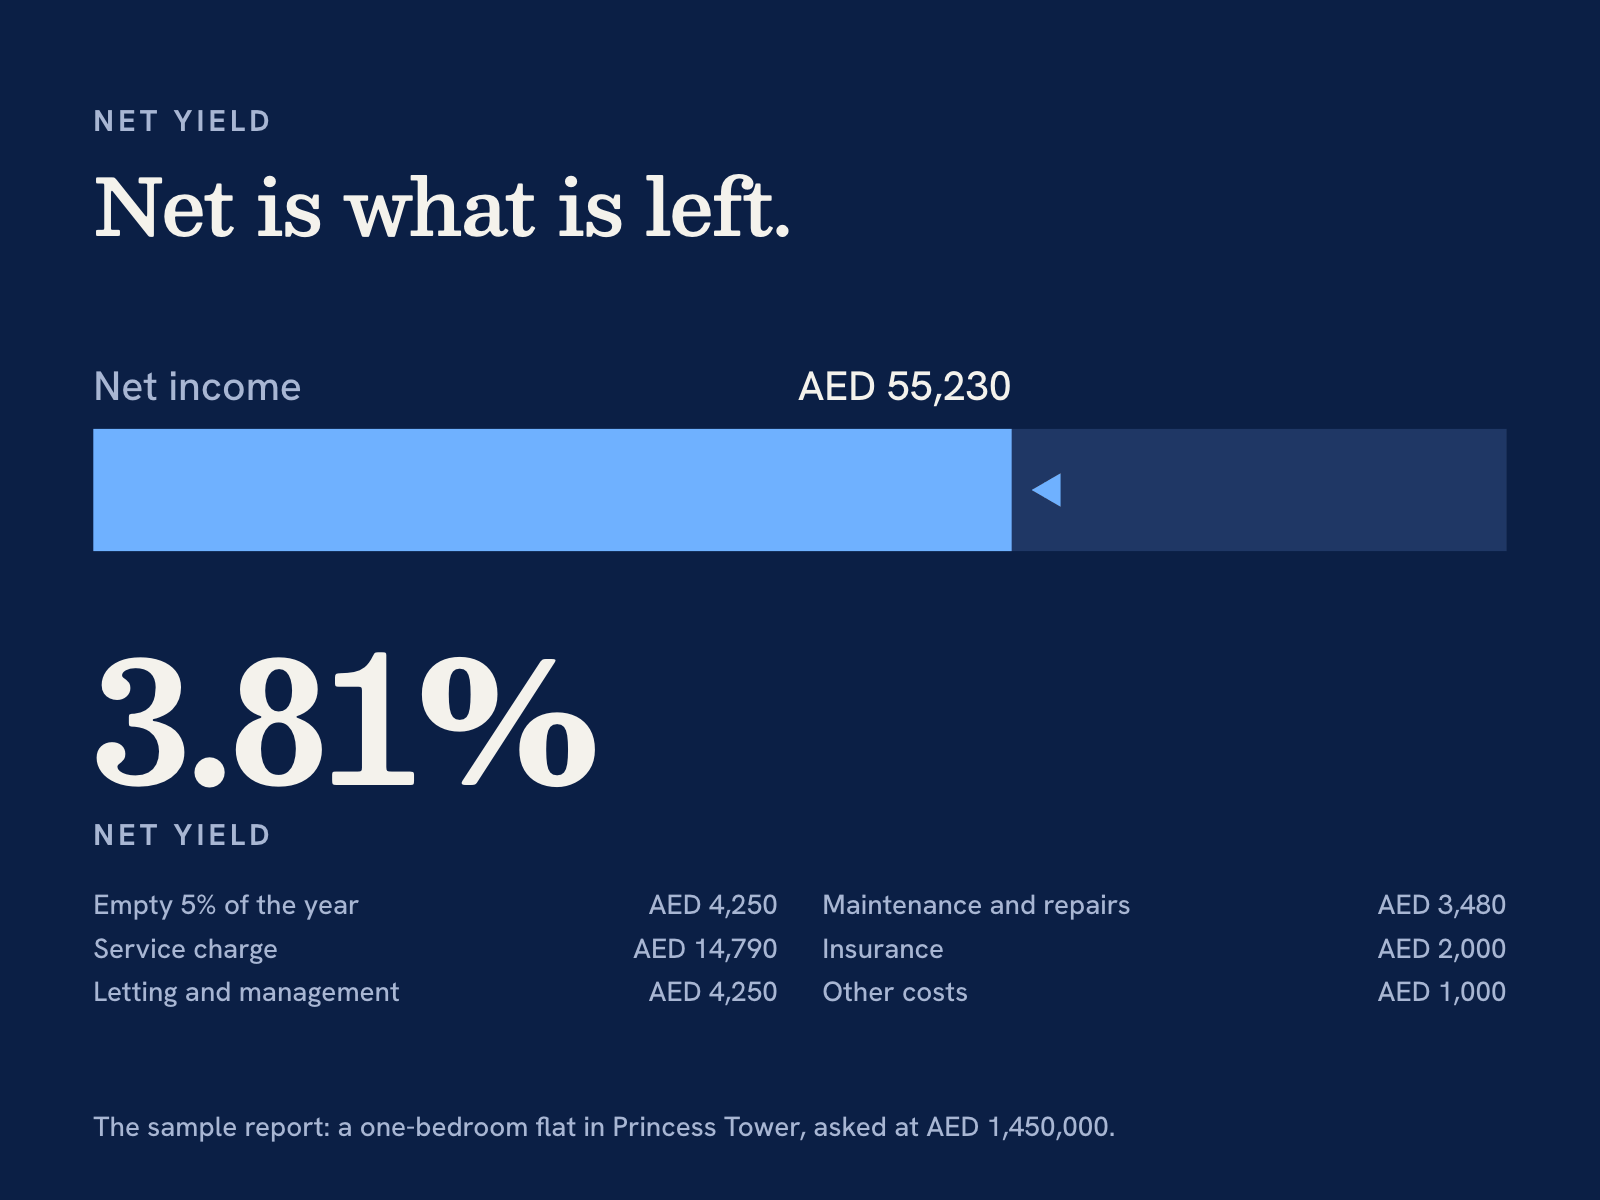
Net yield, workedCosts of holding: empty 5% of the year AED 4,250, service charge AED 14,790, letting and management AED 4,250, maintenance and repairs AED 3,480, insurance AED 2,000 and other costs AED 1,000. The mortgage is not one of them: net yield is the same for a cash buyer. Worked on the sample report’s property: a one-bedroom flat of 870 sq ft in Princess Tower, Dubai Marina, at AED 1,450,000. The asking price and the rent expected are an example of ours, entered for the sample report. They are not a listing. See also gross yield, net operating income, cash-on-cash return. Guide: Gross yield, net yield and cash flow.
- No objection certificateAlso NOC
A developer’s written consent to a resale. It is customarily the seller’s cost, and each developer sets its own fee.
See also transfer.
O
- Occupancy
The share of the year a property is let: 100% less vacancy.
See vacancy, break-even occupancy.
- Off-plan
A property bought from a developer before it is finished. The price is paid in instalments under a payment plan, and there is no rent until handover.
See also Oqood, payment plan, handover, escrow account. Guide: Off-plan and payment plans.
- Operating expenses
Another name for holding costs.
See holding costs.
- Oqood
The Dubai Land Department’s register of off-plan sales. A purchase is recorded there until the property is finished and a title deed can be issued.
See also off-plan, title deed. Guide: Off-plan and payment plans.
P
- Payment plan
The schedule on which an off-plan buyer pays the developer: a sum on booking, instalments during building, and a balance at or after handover. A report sets out each instalment and the day it falls due.
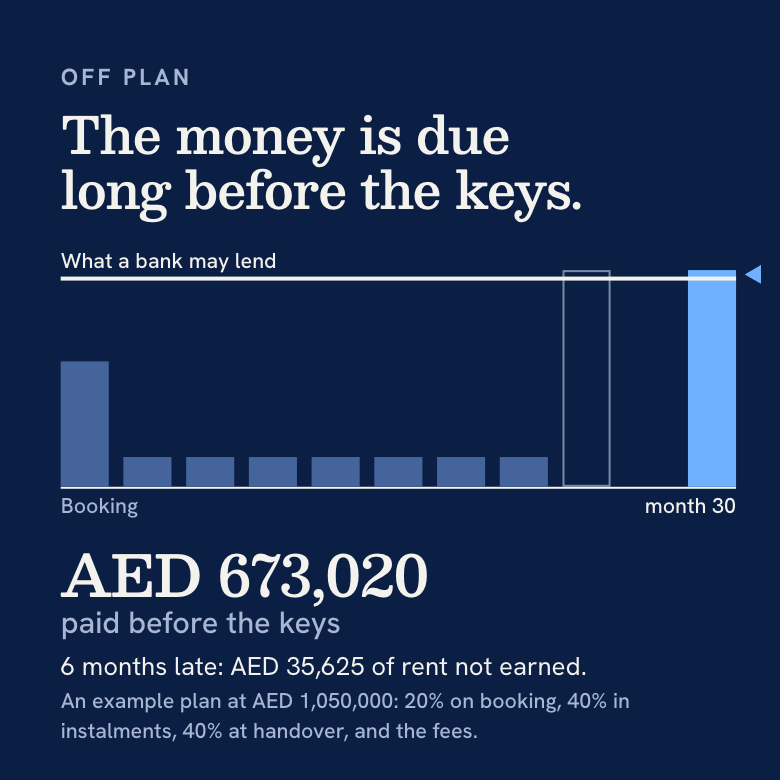
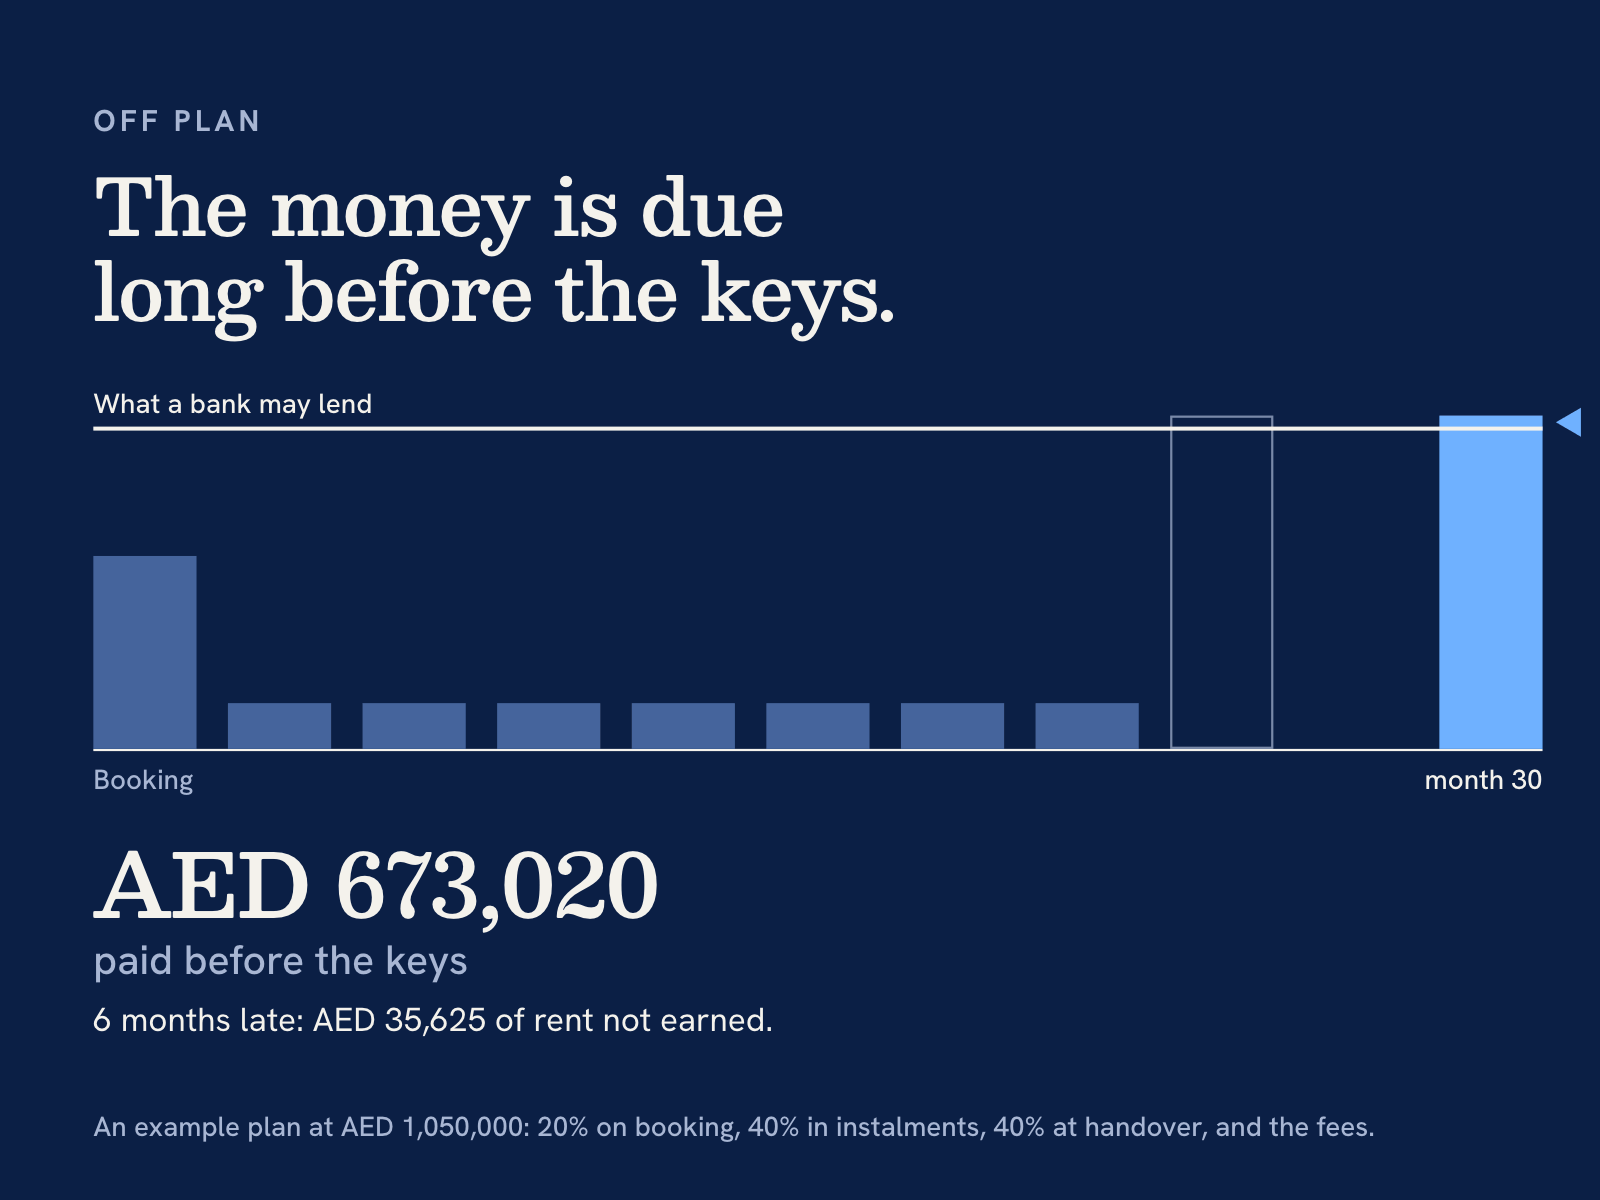
An off-plan schedule20% on booking, 40% in instalments while it is built and 40% at handover, with the fees due at each end. In the report’s sums the mortgage starts at handover, so what is due before the keys is the buyer’s own money: AED 673,020 here. At handover a bank may lend up to AED 420,000 of the AED 437,110 then due. A handover 6 months late is AED 35,625 of rent not earned. An example of ours: a one-bedroom flat bought off plan in Jumeirah Village Circle at AED 1,050,000, with rent expected of AED 75,000 a year. It is not a listing. See also off-plan, handover. Guide: Off-plan and payment plans.
- Price per square foot
The price divided by the floor area. It lets you set homes of different sizes side by side.
Price ÷ floor area
What it leaves out. The floor, the view, the condition and the service charge.
See also rent per square foot.
- Principal
The amount borrowed, as distinct from the interest charged on it.
See also amortisation, equity.
- Property management fee
What a letting agent charges to find tenants, collect the rent and arrange repairs. The calculator starts from 5% of the yearly rent.
See also holding costs.
R
- Refinancing
Replacing one mortgage with another, most often for a lower rate. The first bank may charge an early settlement fee, and the new one has fees of its own.
See also early settlement, mortgage.
- Registered price
What a buyer paid, as the land department recorded it at the transfer. A report sets the asking price beside the registered prices of homes like it.
What it leaves out. The floor, the fit-out and the condition of each home sold.
See also asking price, median, Data Dubai. Guide: How to read a YieldPulse report.
- Registered rent
The rent on a tenancy contract registered with Ejari. A report sets the rent you expect beside the registered rents of homes like it.
What it leaves out. The condition of each home. A renewal can also sit below what a new tenant would pay.
See also asking rent, Ejari, median. Guide: How to read a YieldPulse report.
- Registration trustee
An office approved by the Dubai Land Department where a sale is transferred. Its fee with VAT is AED 4,200, or AED 2,100 for a property under AED 500,000.
See also transfer, buying costs.
- Rent per square foot
A year’s rent divided by the floor area. It lets you set what homes of different sizes let for side by side.
Yearly rent ÷ floor area
See also price per square foot.
- Rental yield
Rent as a share of price. Ask whether a quoted yield is gross or net: the gap between the two can be wide.
See gross yield, net yield.
- RERA
The Real Estate Regulatory Agency, the arm of the Dubai Land Department that regulates developers and brokers. Its rental index sets how far a rent may rise when a tenancy is renewed.
See also Dubai Land Department, Ejari.
- Return on investmentAlso ROI
The total return over the years you hold a property, as a share of the cash you put in.
Total return ÷ cash needed × 100
What it leaves out. How long it took. The same figure over five years and over ten are different results.
See also total return, internal rate of return. Guide: Gross yield, net yield and cash flow.
S
- Service charge
What the owners of a building, not the tenants, pay each year for its upkeep: cleaning, security, lifts, the pool, the reserve for repairs. The calculator starts an apartment in Dubai at AED 17 a sq ft, and a report uses the building’s own filed figure where there is one.
Rate per sq ft × floor area
What it leaves out. Repairs inside your own property and, in some buildings, the cooling.
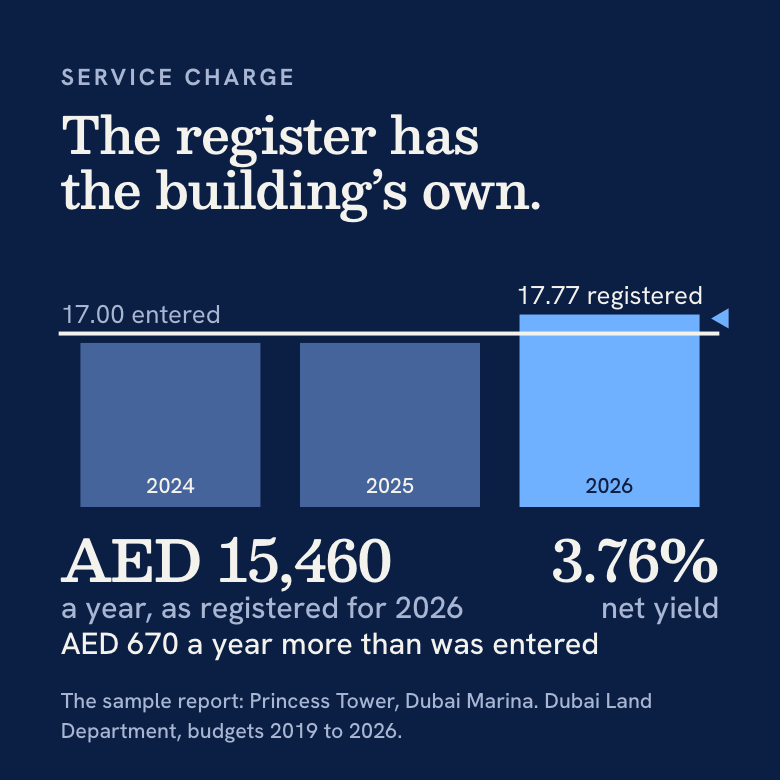
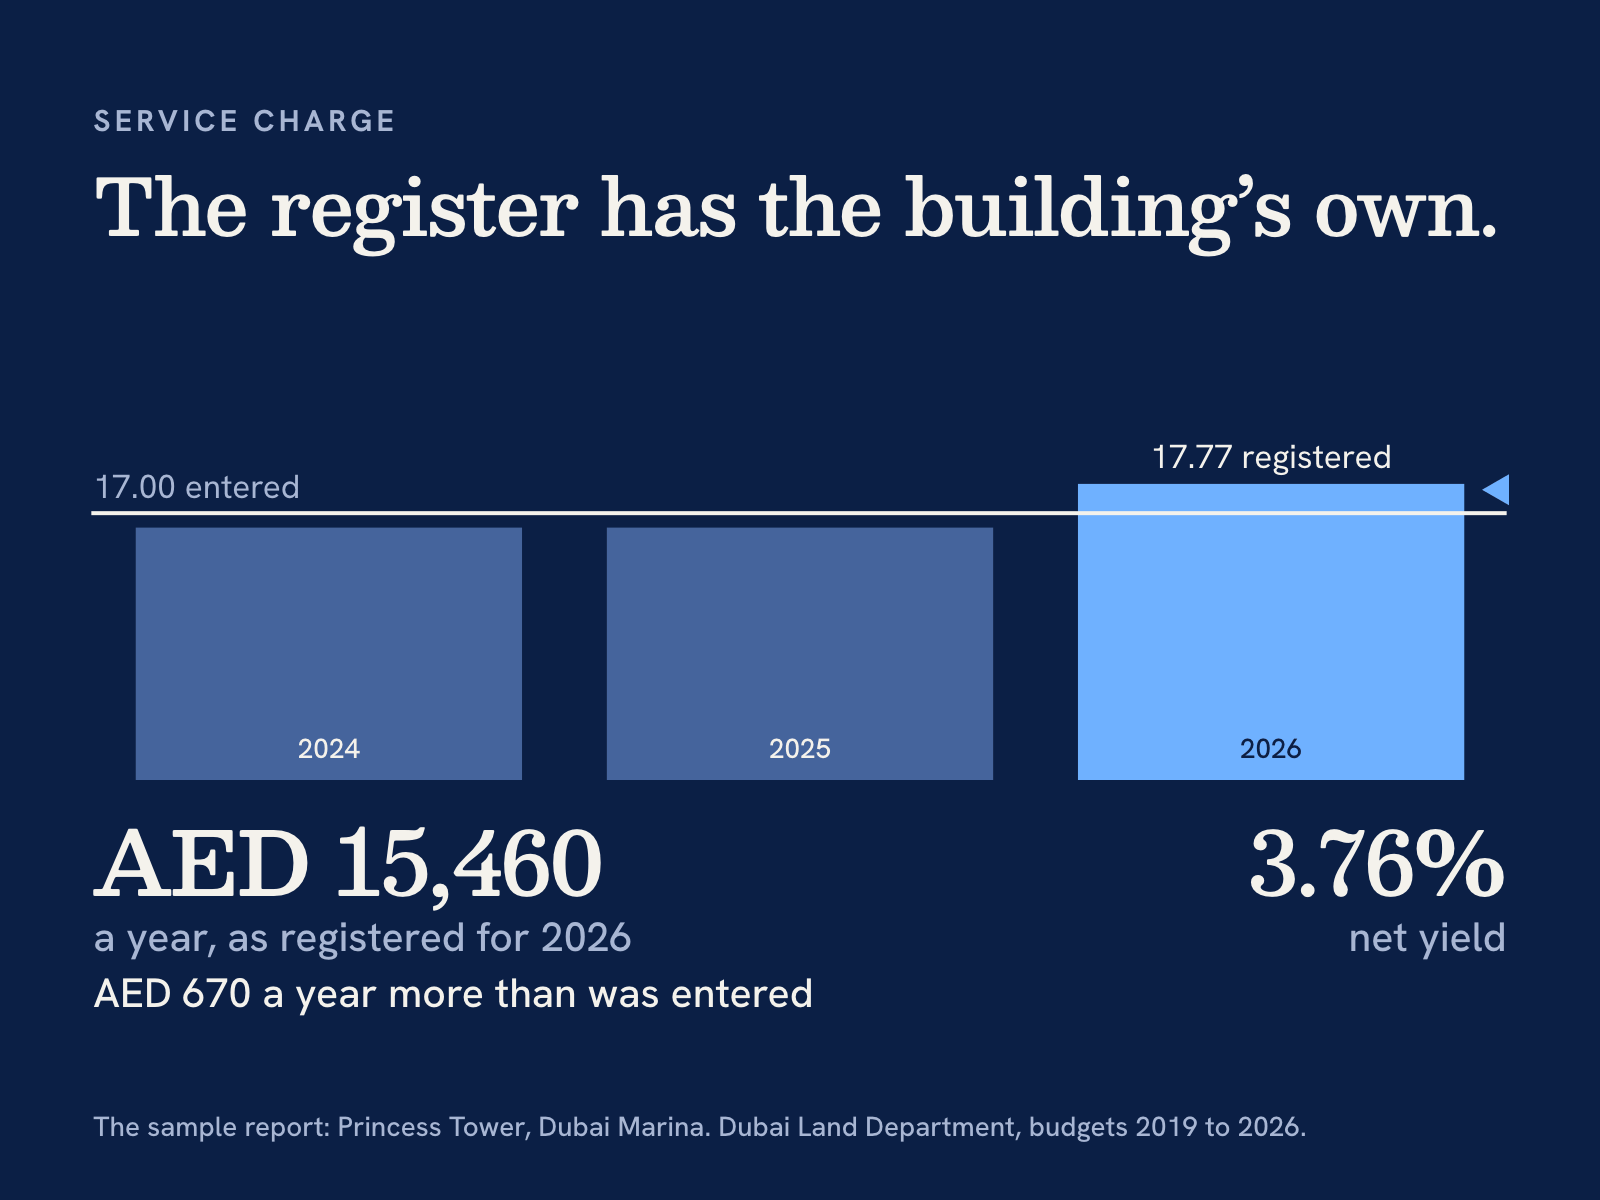
The building’s own chargeEvery dirham of service charge comes off net income. On the register’s figure this flat costs AED 670 a year more to hold than was entered, and its net yield is 3.76%, not 3.81%. Dubai Land Department, Owners Association Service Charges, open data via Data Dubai, budgets 2019 to 2026. Worked on the sample report’s property: a one-bedroom flat of 870 sq ft in Princess Tower, Dubai Marina, at AED 1,450,000. The asking price and the rent expected are an example of ours, entered for the sample report. They are not a listing. Registered figures read . Contains information originated by the Dubai Land Department and the Dubai Data and Statistics Establishment, obtained from Data Dubai (https://data.dubai) under its Open Data Licence. Every figure is YieldPulse’s own calculation from that information. YieldPulse is an independent product. It is not produced by, affiliated with, authorised by or endorsed by the Dubai Land Department, the Dubai Data and Statistics Establishment, Data Dubai or the Government of Dubai. See also holding costs, chiller charges, jointly owned property. Guide: Service charges.
- Strata title
Another name for jointly owned property.
- Stress test
The same sums worked again on worse terms: a lower rent, a higher mortgage rate, an empty flat and a lower sale price. It shows what you would be up or down if things went against you.
What it leaves out. How likely any of it is. It is a stated test, not a forecast.
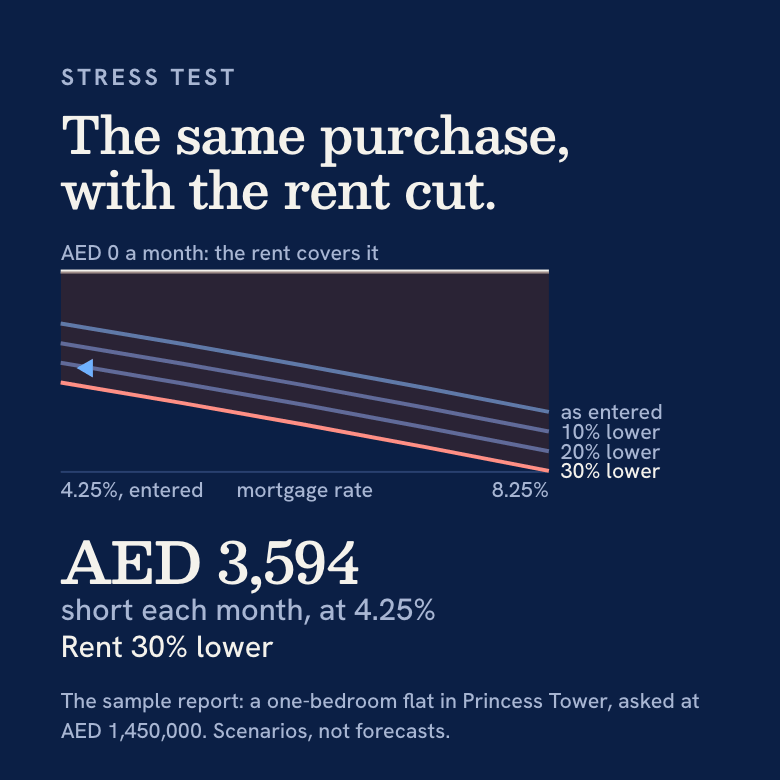
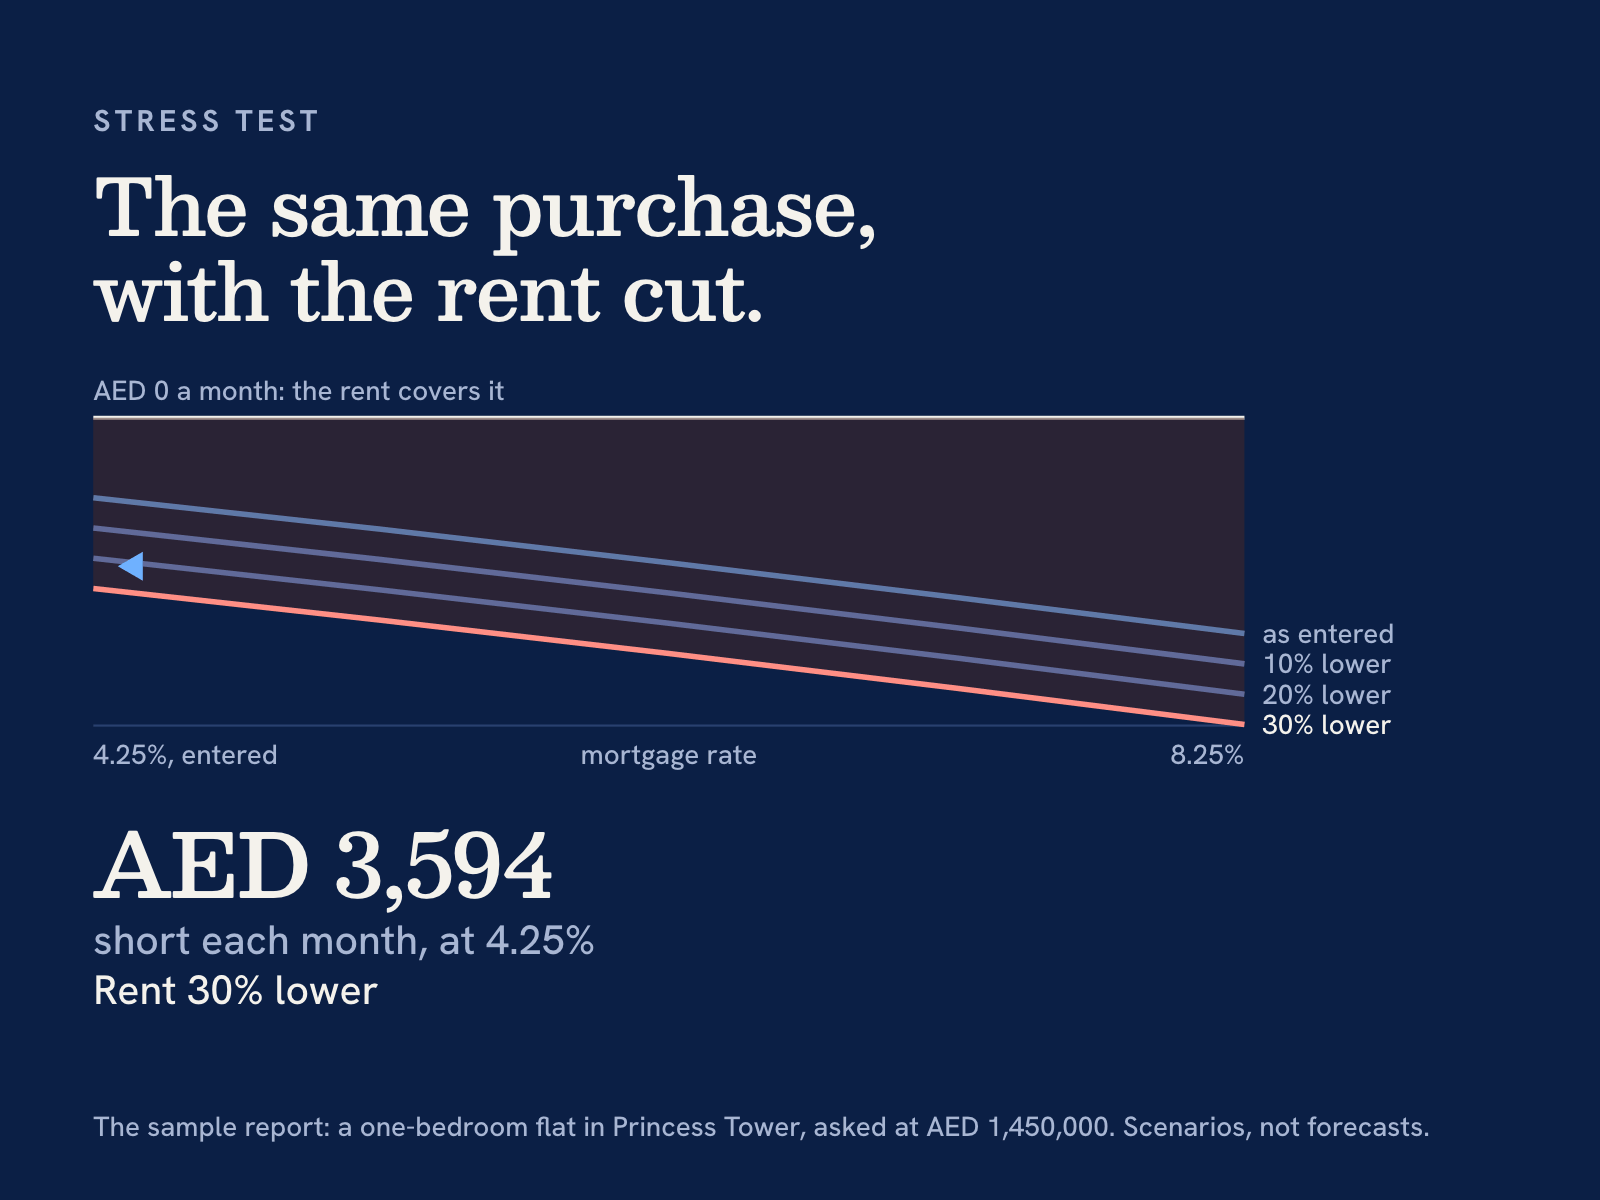
The stress test, workedEach line is the same purchase with the rent cut: how much the buyer adds each month, from the mortgage rate entered (4.25%) up to 8.25%. With the rent as entered that is AED 1,682 a month; 30% lower and it is AED 3,594. Stated tests, not forecasts. Worked on the sample report’s property: a one-bedroom flat of 870 sq ft in Princess Tower, Dubai Marina, at AED 1,450,000. The asking price and the rent expected are an example of ours, entered for the sample report. They are not a listing. See also capital growth, total return. Guide: How to read a YieldPulse report.
T
- Tenancy contract
The agreement between landlord and tenant: the rent, how it is paid, the term and who repairs what. In Dubai it has to be registered with Ejari.
See also Ejari.
- Title deed
The Dubai Land Department’s certificate naming a property’s owner. The department charges AED 250 for the deed, AED 250 for the map and AED 20 in knowledge and innovation fees: AED 520 in all.
- Total return
What a purchase has made or lost by the day you sell: the sale price, less the loan still owed, the selling costs and the cash you put in, with each year’s cash flow added or taken off.
What it leaves out. The sale price itself, which nobody knows in advance.
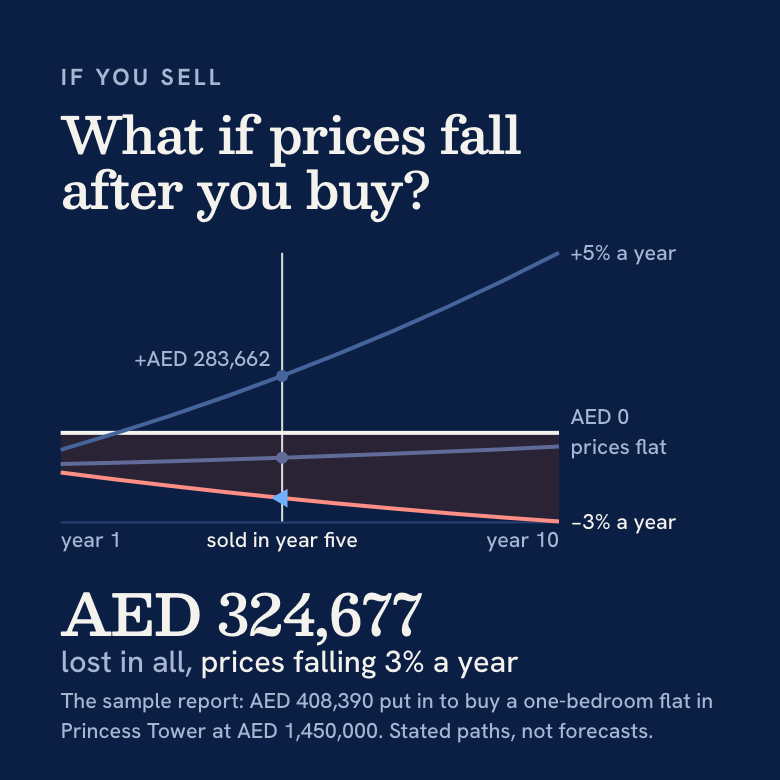
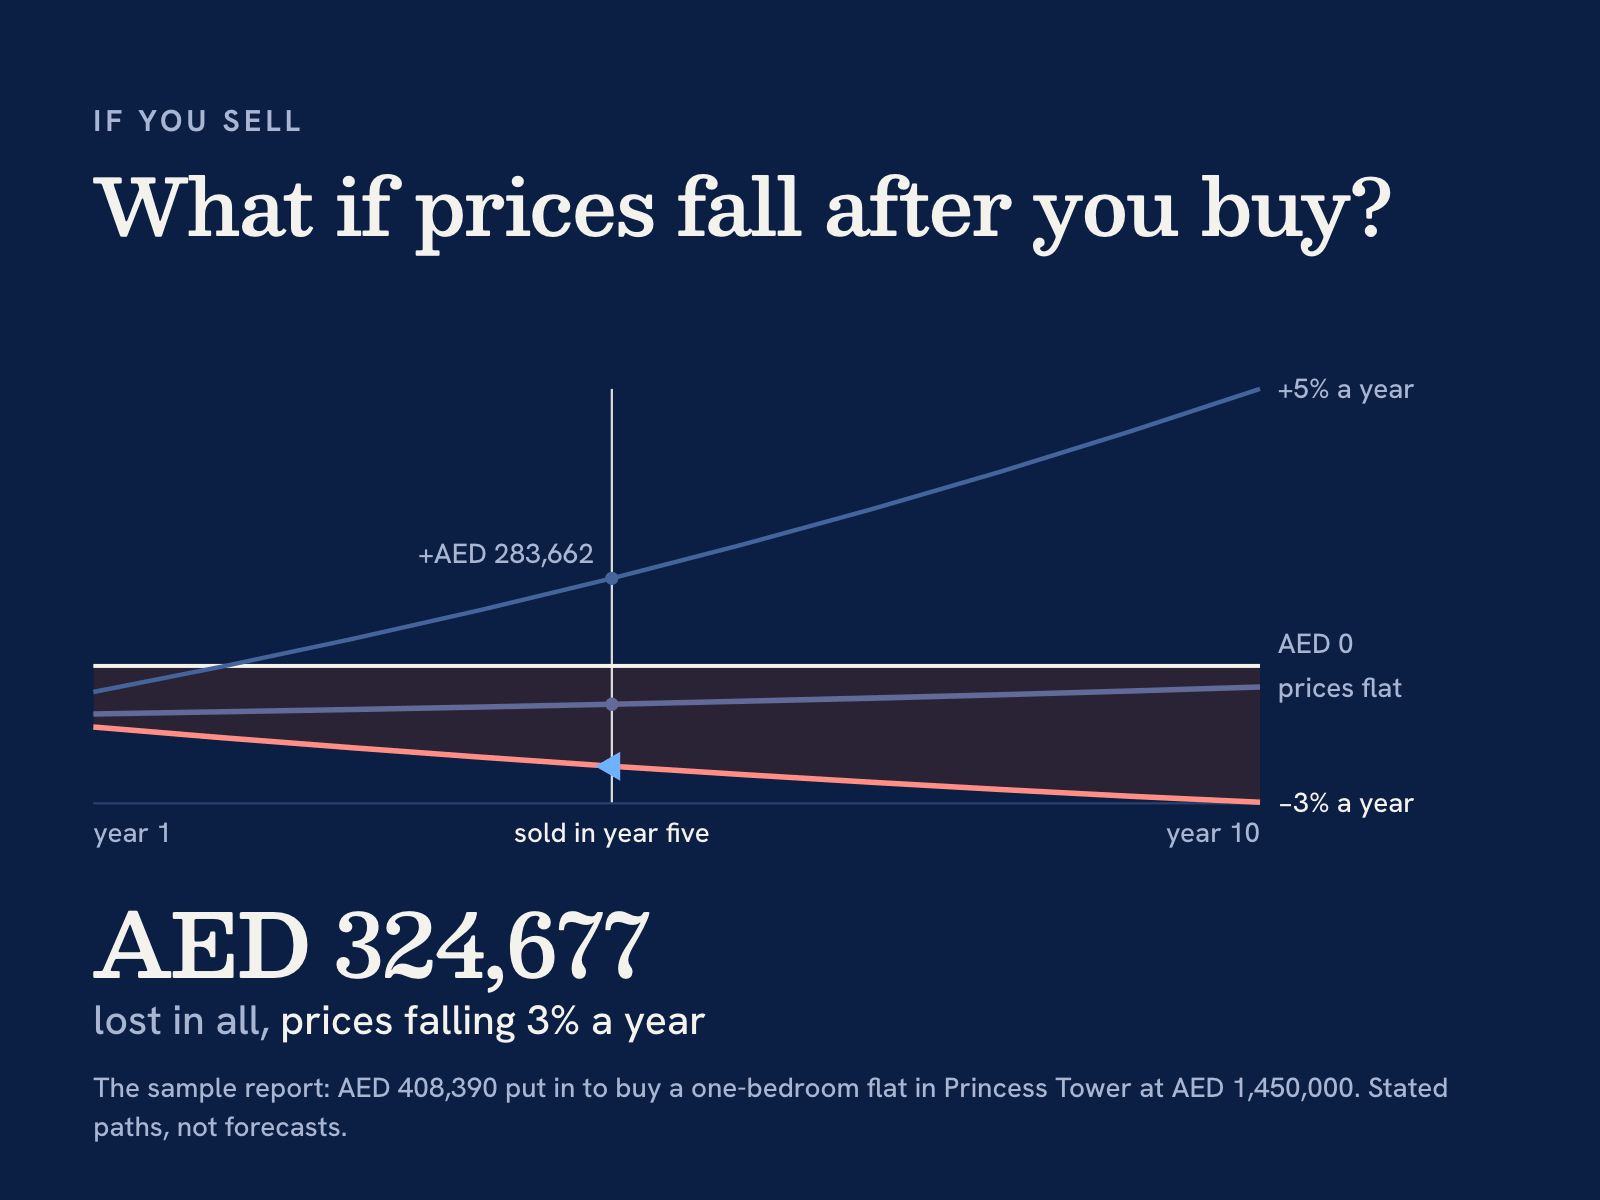
If you sellEach line is the same purchase sold in a different year, on one stated path of prices: what the buyer has made or lost in all on the AED 408,390 put in, with the loan repaid, the costs of selling paid and every year’s cash flow counted. The figures are for a sale in year five. Prices rise 5% a year: AED 283,662 made. Prices stay where they are: AED 124,143 lost. Prices fall 3% a year: AED 324,677 lost. The paths are the ones the sample report states. None is a forecast; rents rise 2% a year where prices rise and stand still otherwise. Worked on the sample report’s property: a one-bedroom flat of 870 sq ft in Princess Tower, Dubai Marina, at AED 1,450,000. The asking price and the rent expected are an example of ours, entered for the sample report. They are not a listing. See also return on investment, capital growth, stress test.
- TransferAlso settlement
The day ownership passes. The buyer pays the price and the fees at a registration trustee’s office, and the Land Department issues a title deed in the buyer’s name.
See also registration trustee, title deed, DLD transfer fee.
- Transfer fee
In Dubai, the DLD transfer fee.
See DLD transfer fee.
V
- Vacancy
The share of the year a property stands empty between tenants. The calculator starts from 5% for an apartment in Dubai, which is 18 days.
Empty days ÷ 365 × 100
What it leaves out. How this building has let in practice. The figure is an allowance.
See also occupancy, break-even occupancy.
- Valuation fee
What a bank charges to have the property valued before it lends. The calculator allows AED 3,150 with VAT; each bank sets its own.
See also market value, buying costs.
- Variable rate
A mortgage rate that moves with EIBOR. The monthly payment rises and falls with it.
See also EIBOR, fixed rate.
- Verdict
What a report opens with: yes, no, or only on a condition, with each reason and what would change it. It reads the numbers of one property and is not personal advice.
See also stress test. Guide: How to read a YieldPulse report.
Y
- Yield on cost
Net operating income as a share of the price plus every buying cost. It is lower than net yield, because the fees are counted.
Net operating income ÷ (price + buying costs) × 100
See also net yield, buying costs.